Greece announces 15% transfer tax for third-country buyers
 Michael Mai
·updated 8 Sep 2026
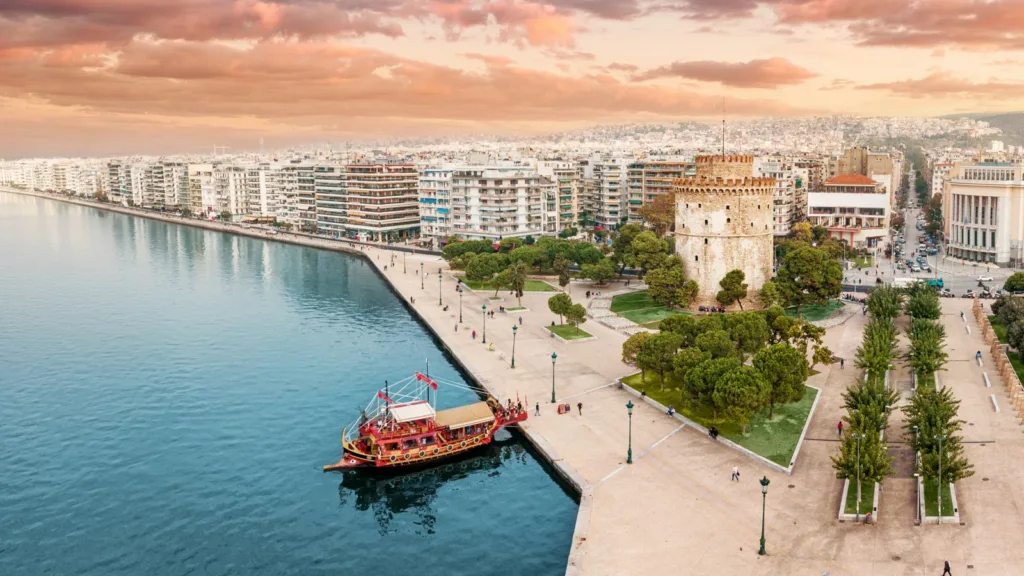
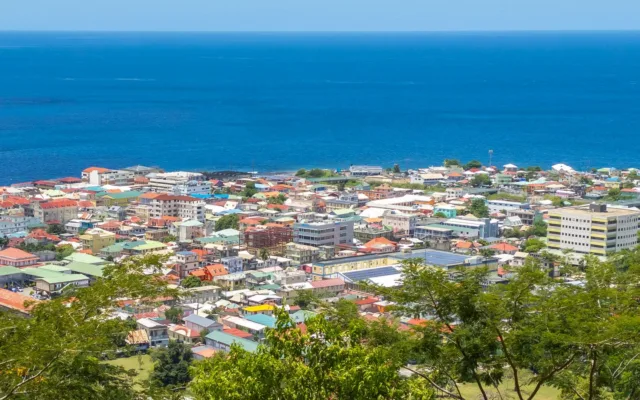
Apartment blocks on the Thessaloniki seafront. The 15% rate was announced at the Thessaloniki International Fair on 5 September 2026, and the Thessaloniki Regional Unit is among the areas where the 800,000 euro threshold applies.
From 1 July 2027, against today's 3%, the announced rate would add €96,000 in tax on an €800,000 taxable value — the investor threshold in Attica, Thessaloniki and the larger islands. No bill is yet tabled.
Greek press reporting of the Prime Minister’s speech to the 90th Thessaloniki International Fair on 5 September 2026 says he announced that the property transfer tax charged to third-country nationals will rise to 15%, against the 3% general rate now in force. Officials setting out the package on Monday 7 September put the start date at 1 July 2027; reports of the speech two days earlier had given 1 January 2027. As at 8 September no bill had been tabled and no text of the measure had been published.
What was announced, and what was not
The tax was one item in a package the government values at about €2.2 billion for 2027, of which the tax reliefs are put at €884 million. Third-country national is the term EU law uses for a person who is not a citizen of a member state; where it leaves nationals of the European Economic Area and Switzerland, and people who hold an EU citizenship alongside another, is among the open points below.
An announcement in a speech is not a rule. Automated requests to the Prime Minister’s websites returned an access refusal on 7 September, so the speech was not read directly, and the rate, the date and the class of buyer in this article rest on Greek reporting published on the day. None of that reporting sets out how the charge would be constructed.
What the tax is today
Greece charges 3% on transfers of real estate under article 4 of compulsory law 1521/1950, ratified by Law 1587/1950. The charge is assessed on the greater of two figures: the price written into the contract, or the objective value the tax administration assigns to the property. A levy in favour of municipalities is charged in addition to the tax itself.
That levy is one of the things the announcement leaves open — whether 15% replaces the 3% headline rate alone, or is computed on some other basis, and what becomes of the municipal charge underneath it. Every figure below therefore sets headline rate against headline rate and excludes the levy.
Why this lands on the investor route
The permanent residence permit for investors, commonly called the Golden Visa, is open only to third-country nationals. The Migration Ministry’s circular of 24 September 2024 says so in its subject line. Every applicant for that route is therefore a member of the class the announcement names, though the reverse does not hold, and whether applicants or existing holders are covered is one of the open points below.
The same circular sets the sums, applying article 100 of Law 5038/2023 as amended by article 64(1) of Law 5100/2024. The minimum acquisition value is €800,000 in the Attica Region, the Thessaloniki Regional Unit, the Mykonos and Thira Regional Units, and islands with more than 3,100 inhabitants at the last census; Euboea counts as an island area and falls in that band. Elsewhere it is €400,000. On both, built property or property with a building permit must offer at least 120 m² of main space. A third route sets €250,000 where the main spaces are converted to residential use, the conversion completed on or after 5 April 2024 and before the application is filed; there the floor area does not apply. All three routes require the minimum value to be met by a single property.
The load-bearing detail is what those thresholds measure. The circular sets each as the minimum acquisition value of the property at the time of acquisition. Transfer tax sits outside that figure. For a purchase at exactly the applicable minimum, an investor cannot reduce the price to offset a larger tax bill without falling below the value the route requires.
The arithmetic
If the announced headline rate is enacted as reported, and assuming the taxable value equals the acquisition value, the comparison at each qualifying level would be:
- €800,000: €24,000 at 3% against €120,000 at 15%, a difference of €96,000.
- €400,000: €12,000 against €60,000, a difference of €48,000.
- €250,000 conversion route: €7,500 against €37,500, a difference of €30,000.
Notary, land registry and legal costs sit outside all three, as does the municipal levy discussed above. On those assumptions the outlay at the €800,000 band would move from roughly €824,000 to roughly €920,000 before those other costs. The property, the permit and the qualifying threshold are all held constant in that comparison; only the assumed rate changes.
Six questions the announcement does not answer
- Whether holders of an existing Greek residence permit, including investors renewing or buying again, fall inside the 15% rate or outside it.
- Whose nationality is tested where the buyer is a company registered in Greece or in another member state.
- What commencement and transitional rules would apply to purchases agreed or completed around 1 July 2027.
- How nationals of European Economic Area states outside the Union, and of Switzerland, would be treated.
- Whether the 15% replaces the 3% headline rate alone, and what happens to the municipal levy.
- How a person holding both a third-country and an EU nationality is treated.
The sources reviewed to 7 September resolve none of these.
What to watch
The document to wait for is the bill, and after it the article that fixes the rate, the definition of the buyer and the transitional rule. What can be said meanwhile is the sequence. The 2024 amendment raised the standard investor thresholds to €800,000 and €400,000 and redrew the bands they apply to; it barred short-term letting of qualifying property within the sharing economy, subject to its own exceptions; and a five-fold rise in transfer tax has now been announced for a date ten months away, its coverage and exemptions unresolved. Anyone timing a Greek purchase around that date is timing it against a rate that has been announced and a transitional rule that has not been written.
Updated 8 September 2026: the start date is 1 July 2027, not 1 January 2027 as first published on 7 September. Officials setting out the package on Monday 7 September gave that date; the earlier figure came from reports of the Prime Minister’s speech of 5 September.
Read this article in Vietnamese
The Legation Times writes its content from published documents; nothing here is legal, tax or investment advice. Spotted an error? Send a correction request; for content rights, send a takedown request.