San Marino ratifies residence rewrite whose final text is unpublished
 Edward Nguyen
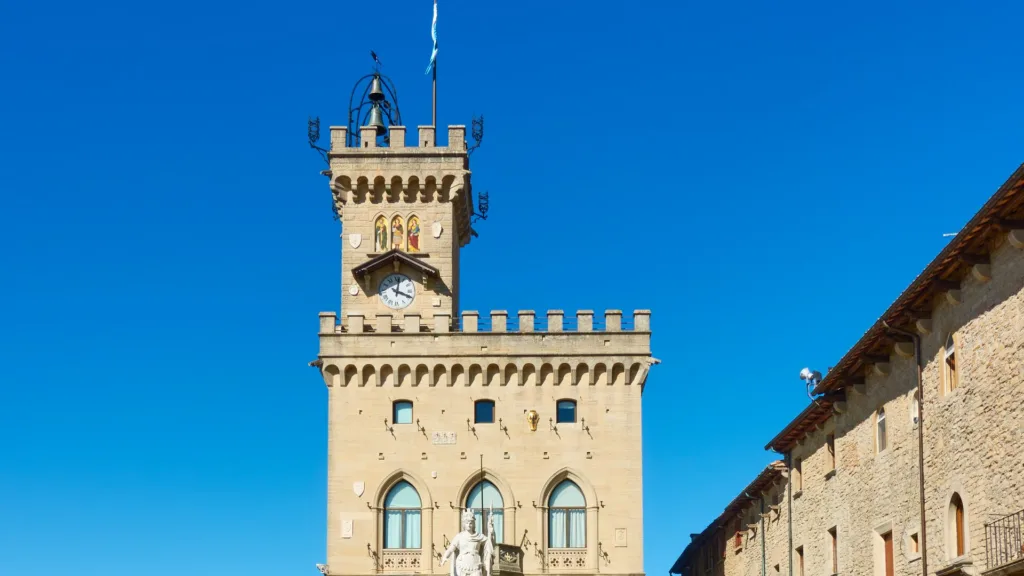
The Palazzo Pubblico on Piazza della Libertà, seat of San Marino's Great and General Council — illustration. The Council ratified Delegated Decree 115/2026 with amendments on 23 September 2026.
The Council approved amendments on 23 September 2026 covering the atypical-residence tax and residence for economic reasons; the revised decree awaits promulgation.
San Marino’s parliament, the Great and General Council, ratified Delegated Decree 115 of 10 August 2026 with amendments on 23 September 2026. A government proposal filed on 23 September 2026 would remove the sector-based hiring thresholds for residence for economic reasons, the permit for foreign nationals who run a company in San Marino, but the Council approved it after reformulation. Its final wording was unavailable on 25 September 2026, and the Council’s record showed the revised decree awaiting promulgation.
Where the decree stands
The decree was published and took effect on 10 August 2026. The Council’s record for its ratification states that it was “ratificato con emendamenti” and gives its current status as “In attesa di promulgazione del nuovo testo del decreto”: the new text of the decree is awaiting promulgation.
According to the AskaNews report of the session, the Council approved four amendments. The amendment on residence for economic reasons was approved after a suspension to reformulate its text. This article therefore describes that amendment as filed on 23 September 2026; the wording finally adopted has not been published.
The original decree: the atypical residence tax
The decree as issued on 10 August 2026 concerned a different permit, the atypical residence under a favourable tax regime in Article 16-ter of Law 118 of 2010. Holders pay a substitute tax on income produced abroad instead of San Marino’s general income tax.
The rate, the floor and the ceiling were not new. The consolidated text of 3 June 2025 already set the tax at 7 per cent of “netto frontiera”, with a minimum of 10,000 euros and a maximum of 100,000 euros for each tax year. The decree added that the tax is always due for every tax year of the residence. The Foreign Affairs Minister’s report to the Council, signed by Luca Beccari, says the change was to make payment more certain for the offices that check and collect it.
The decree expressly applies the regime to people granted an extension of the principal applicant’s residence, excluding children who are fiscally dependent on that applicant. The principal applicant cannot claim the tax deduction under Article 16(1) of Law 166 of 2013. Children who cease to be fiscally dependent enter the regime automatically from the following tax year until consolidation under Article 16-ter(14). The decree applies from the 2026 tax year.
An amendment approved on 23 September 2026 adds that the tax is due even where San Marino’s conventions against double taxation make that foreign income non-taxable in San Marino.
Residence for economic reasons: what the filed proposal would change
The permit is in Article 22-bis of Law 71 of 2013. The comparison below sets the consolidated text of 3 June 2025 against the government proposal filed on 23 September 2026.
The 2025 text requires one permanent full-time hire from San Marino’s job-placement lists if the company is in a sector designated for incentives, and three if it is not. The filed proposal would require either one full-time employee or two part-time employees whose combined hours equal a full-time post, all resident in San Marino and employed on permanent contracts, without sector distinctions. Hiring the applicant or family members would not count.
The proposal would repeal Articles 19 and 20 and Annex A of Delegated Decree 137 of 2017. Article 19 generally required the company’s activities to correspond to at least two codes on the Annex A list, with an alternative for specified agri-food activities that combine one listed code with wholesale of the same goods. Article 20 set a flat health contribution of 350 euros a month per person and required insurance of at least 50,000 euros of annual cover per person for medical services outside a specified schedule. Under the proposal, holders would bear the full cost of health care, in the manner set by the Social Security Institute, until their residence is consolidated.
The ownership test would be tightened in one word: the applicant would have to hold at least 51 per cent of the company’s capital directly.
Consolidation would require an application. The 2025 text provides for consolidation after ten years, subject to fulfilled commitments and checks on eligibility and habitual residence. The filed proposal keeps those conditions but requires a written application with identity documents, criminal record and pending-proceedings certificates from San Marino and the applicant’s country, and a report on the business.
The proposal keeps the initial guarantee of 75,000 euros and the requirement to raise it to 150,000 euros, or replace it with qualifying property, within two years of obtaining residence. It would require the property to serve as the business premises or the beneficiary’s home within twelve months of the grant of residence, while retaining the registered privilege in favour of the state. It keeps a maximum of 50 grants a year, excluding qualifying family members and adjustable each year by delegated decree. Both texts bar applicants with aggregate formally enrolled debts exceeding 20,000 euros across themselves and businesses in which they hold interests in San Marino, including indirectly, unless an authorised payment arrangement is duly honoured. Holders have ninety days to remedy the breach before referral for revocation.
The filed proposal would give existing holders six months from the ratification date to comply, and would instruct the government to adopt, by 31 December 2027, a decree amending Article 22-bis again.
Two further amendments
The Council also approved an amendment requiring the government to report on all types of residence in the decree to the Council’s foreign affairs committee by 31 January and 31 July each year, and an amendment repealing two provisions of Delegated Decree 5 of 2016, which this article has not examined.
Limits of this reading
The final text of the ratified decree was not available when this article was checked on 25 September 2026. The comparison uses the Council’s consolidated text of 3 June 2025, which the Council states is not an authentic copy, and does not cover any amendment made between that date and 10 August 2026.
The Legation Times writes its content from published documents; nothing here is legal, tax or investment advice. Spotted an error? Send a correction request; for content rights, send a takedown request.